Frisco, TX · Commercial loan broker

Business loans and funding for Frisco businesses

Can a broker help me compare business loan costs in Frisco? Yes. A commercial-loan broker sources quotes from multiple lenders, models total repayment for each option, and itemizes origination fees, servicing fees, and third-party costs.

Creekfield Lenders is a local commercial loan broker in Frisco, TX. We match business owners across Frisco, The Colony, Prosper, and Little Elm with the right lenders for SBA loans, working capital, equipment financing, and invoice factoring, with a same-day answer and no application fee.

  • Quick, no-fee application
  • No prepayment fees
Apply for Loan
How Much You Need
$25,000$150,000$5,000,000
6 Months24 Months60 Months
7%15%30%
Pay Monthly$7,270
Total Pay Back$174,480
Apply For Loan

Estimate only. Creekfield Lenders is a commercial loan broker, not a lender; actual rate, term and payment depend on the lender and your approval.

Company Introduction

Our loans will fill your business goals

Creekfield Lenders brokers commercial financing for businesses across Frisco, The Colony, Prosper, and Little Elm. Tell us the goal, we position your file with the right lenders, and you choose from real options with a local advisor, no application fee and no hard credit pull to start.

SBA loans, working capital, equipment financing, and invoice factoring, from $25K to $5M.

See all loan programs →
Who Creekfield Lenders Serves in Frisco

78% of Frisco's commercial corridors along Preston Road and the Dallas North Tollway house businesses under fifty employees, and those firms report capital access as their top growth constraint. Creekfield Lenders is an independent commercial-loan broker headquartered at 8560 Belleview Dr, Plano, TX 75024, serving Frisco and nearby Allen, Fairview, Hackberry, Hebron, Oak Point, and Providence Village. We work with retailers in The Gate district, medical offices near Frisco Square, contractors serving the Legacy West buildout, and service companies operating along the Sam Rayburn Tollway. Whether you need $50,000 to expand inventory or $2 million to acquire a competitor, we match your scenario to the right lender and walk you through every cost component before you sign.

Loan programs

Core Financing Programs We Broker

Creekfield Lenders brokers seven major commercial-loan products. Each program carries distinct pricing structures, collateral requirements, and repayment terms. We explain those differences in plain language so you can compare total cost, not just monthly payment, and choose the option that preserves the most cash flow for operations.

For details on fast-turnaround options, visit our working capital loans page.

Read more

Learn more on our equipment financing page.

Explore revolving credit options on our business line of credit page.

SBA 7(a) Loans

The SBA 7(a) loan program remains the most flexible government-backed option for business acquisitions, working capital, and real estate purchases. Loan amounts range from $50,000 to $5 million, repayment stretches up to twenty-five years for real estate and ten years for equipment, and the Small Business Administration guarantees a portion of each loan to reduce lender risk.

Learn more

Working Capital Loans

Working capital loans bridge the gap between receivables and payables. These short-term facilities typically run six to eighteen months and fund payroll, inventory purchases, marketing campaigns, or seasonal peaks. Frisco businesses along Main Street and in the Rail District use working capital to stock up before holiday shopping surges or to cover payroll when a large invoice payment delays thirty days.

Learn more

Equipment Financing

Equipment financing ties loan repayment directly to the asset being purchased. Lenders advance 80% to 100% of the invoice price for machinery, vehicles, computers, medical devices, or restaurant equipment, then secure the loan with that same asset. Terms mirror the equipment's useful life, three to seven years for tech and vehicles, ten to fifteen years for heavy machinery.

Learn more

Business Line of Credit

A business line of credit offers revolving access to capital you draw and repay as needed. Credit limits range from $10,000 to $500,000, interest accrues only on the outstanding balance, and most lines renew annually with a review of your financials. Frisco service businesses use lines of credit to smooth uneven cash flow, cover emergency repairs, or take advantage of bulk-purchase discounts without tying up reserves.

Learn more

Commercial Real Estate Loans

Commercial real estate loans finance the purchase or refinance of owner-occupied or investment properties. Terms extend ten to twenty-five years, and lenders typically require 20% to 30% down.

Learn more

How it works

The Creekfield Lenders Process

Our four-step brokerage process centers on cost transparency and lender fit. First, we review your financial statements, credit profile, and funding purpose during a no-cost consultation by phone at (972) 478-1909. Second, we identify two to four loan programs that match your collateral, cash flow, and timeline, then model total cost for each option including origination fees, servicing fees, and interest. Third, we submit your complete application package to our network of regional and national lenders, negotiating terms and answering underwriter questions on your behalf. Fourth, we coordinate closing, explain every line of the settlement statement, and remain available post-funding for refinance analysis or additional capital needs.

Why Frisco Businesses Choose a Local Broker

Frisco's rapid commercial growth creates unique financing challenges. New construction along the Cotton Gin corridor and tenant turnover in older centers near Preston and Lebanon mean lenders scrutinize location risk, lease terms, and market comparables more closely than in established submarkets. A broker based fifteen minutes from your business understands those nuances. We know which lenders will finance a startup in a co-working space at The Star, which require two years of tax returns for a franchise near Frisco Fresh Market, and which will subordinate SBA debt to a landlord's build-out lien. That local knowledge translates to faster approvals, fewer surprises, and financing structures that support your next stage of growth.

For a deeper look at our team and approach, visit our About page.

Service area

Service Area Across Collin County

Creekfield Lenders brokers business loans throughout Frisco and neighboring communities including The Colony, Hackberry, Prosper, Hebron, Little Elm, Providence Village, Oak Point, Allen, and Fairview. Our Plano office at 8560 Belleview Dr sits less than ten minutes south of Frisco via the Tollway, making in-person consultations convenient for business owners across northern Collin County. We also serve clients by phone and secure document portal when a drive-time visit isn't practical.

View our complete coverage map on the Service Areas page.

Why us

Why businesses choose Creekfield Lenders

The reasons Frisco owners bring us their financing, in plain terms.

No application fee
You never pay us to shop your file. We are paid by the lender on funded deals, so exploring your options costs you nothing.
Soft pull to start
See where you stand without a hard credit inquiry up front, so checking your options will not affect your score to begin.
Same-day answers
Tell us the amount you need and what it is for, and you will get a same-day read on where you stand.
One file, many lenders
We take your application to a network of lenders instead of a single bank, then bring you offers to compare.
Frisco focus
Local guidance for the Frisco and Plano area. We know the market and match you with lenders that fund businesses like yours.
No obligation
Compare the offers we bring back with no pressure and no commitment to proceed.

Creekfield Lenders is a commercial loan broker, not a lender.

Serving the Frisco area

Local guidance across Frisco, TX

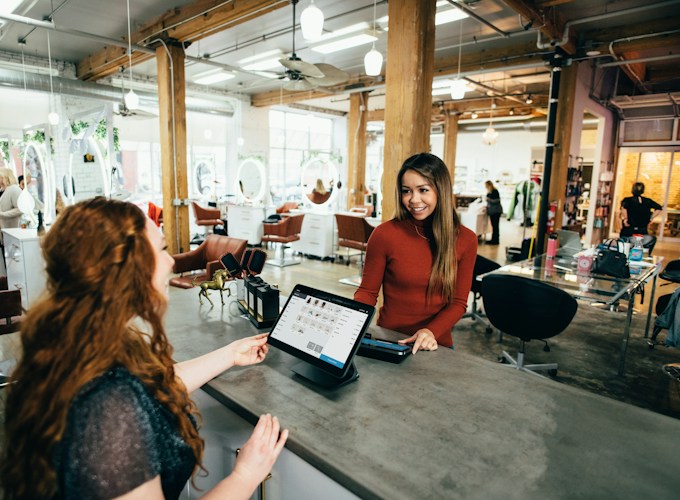
Frisco salon owner taking a card payment at the counter

We know which lenders fund which kinds of Frisco businesses, and we position your file where it fits.

Compare multiple lenders through one broker.

See loan programs →

Market context

By the numbers

78% of Frisco's commercial corridors along Preston Road and the Dallas North Tollway house businesses under fifty employees, and those firms report capital access as their top growth constraint.

01

33 million-plus small businesses form the backbone of U.S. commerce.

SBA Office of Advocacy
02

Most loan applicants request $100,000 or less — the working range for most alternative lenders.

Federal Reserve Small Business Credit Survey
03

Roughly half of applicant businesses needed capital mainly to sustain operations.

Federal Reserve Small Business Credit Survey

Primary federal sources, reviewed 2026.

Common questions

Common questions about business loans in Frisco

What types of businesses qualify for small business loans in Frisco?+
Most for-profit businesses operating in Frisco qualify if they show positive cash flow, acceptable credit, and sufficient collateral. Retailers, medical practices, contractors, professional services, and light industrial firms all secure business funding in Frisco. Startups may access SBA microloans or equipment financing, while established companies often qualify for larger working capital or real estate loans.
How long does business funding take in Frisco?+
Working capital and invoice factoring can close in three to seven business days once documentation is complete. SBA 7(a) loans and commercial real estate transactions typically require four to eight weeks for underwriting, appraisal, and closing. Equipment financing falls in the middle, often funding within two weeks. Creekfield Lenders accelerates every timeline by submitting complete packages and managing lender communication.
Do I need collateral for a business line of credit in Frisco?+
Many business lines of credit require a blanket lien on business assets, accounts receivable, or inventory. Some lenders offer unsecured lines up to $50,000 for businesses with strong credit and two years of profitability. Creekfield Lenders presents both secured and unsecured options, explaining how collateral requirements affect credit limits and pricing so you can choose the structure that fits your balance sheet.
Can a broker help me compare business loan costs in Frisco?+
Yes. A commercial-loan broker sources quotes from multiple lenders, models total repayment for each option, and itemizes origination fees, servicing fees, and third-party costs. Creekfield Lenders provides side-by-side cost comparisons before you commit, ensuring you understand the true expense of each financing path. That transparency helps you preserve working capital and avoid hidden charges that surface at closing. Creekfield Lenders 8560 Belleview Dr, Plano, TX 75024 (972) 478-1909 Independent commercial business-loan broker serving Frisco, The Colony, Hackberry, Prosper, Hebron, Little Elm, Providence Village, Oak Point, Allen, and Fairview. Call today to discuss SBA 7(a) loans, working capital, equipment financing, commercial real estate, business lines of credit, invoice factoring, and more.

Ready to move on funding?

Get matched to the right lending program for your business type and balance.

Apply for funding →
Apply for fundingCall now